From automated notetaking to AI-powered bots, pension admin is evolving, but experts say trust, governance, and fiduciary duty are slowing the pace of adoption
Despite all the noise that AI is making in pension and benefits administration, several experts suggest its presence is smaller and more cautious than the hype suggests.
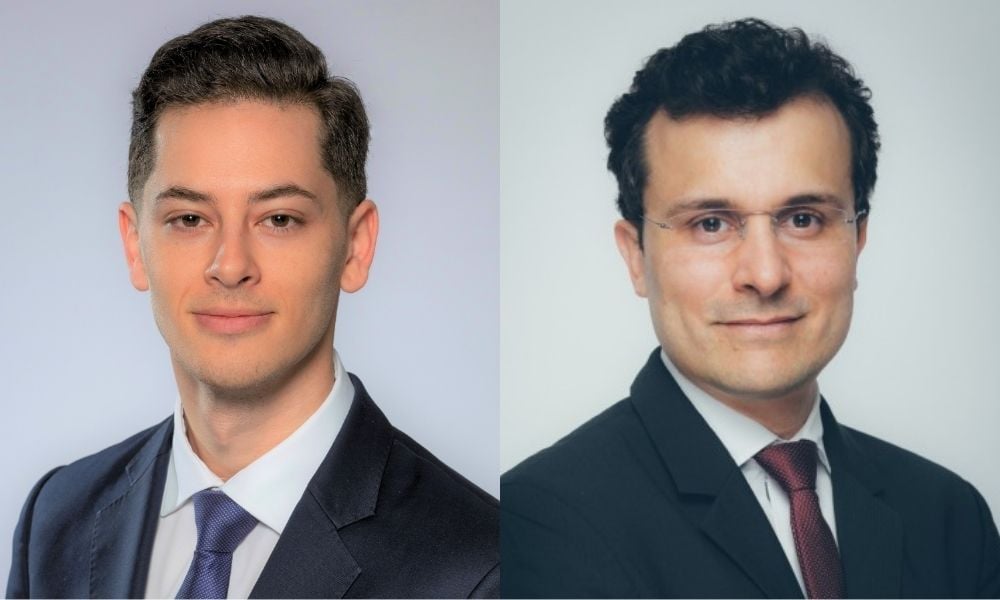
According to Sean Liss, investment consultant at HUB International, AI adoption among plan sponsors has been uneven. Yet, while strategy-level use remains thin, record keepers have started applying generative AI to improve member-facing platforms, making benefit sites easier to navigate and investment content more digestible.
The goal, from a plan sponsor's perspective, is driving engagement and financial literacy among members, though Liss cautioned the technology is still finding its footing.
"It's still a work in progress, but they're making a little bit of ground there," he said.
Gen AI could simplify outdated pension plan sites
"Right now, we're in an age where attention spans are pretty short and pension plans want their members to be educated on their plan. That’s either through understanding their risk tolerances or the investment options that are available to them. But the sites aren’t always easy to navigate," said Liss, adding generative AI could close that gap by simplifying site layouts and making investment content more accessible, which in turn could boost member engagement and plan literacy.
"Those are all things that plan administrators want to see," he added.
Faulty AI output threatens plan member trust
Meanwhile, Sebastien Betermier, finance professor at McGill University and executive director at International Centre for Pension Management (ICPM), identified three AI applications gaining traction in pension administration. The first is automating the note-taking and debriefing process during member calls, allowing engagement officers to cycle through requests faster and maintain a searchable record of interactions. The second is deploying AI-powered bots to field routine member questions without tying up staff.
But the third, he suggests, is trickier because it's not about using AI at all. It's about controlling what AI tells plan members.
"Oftentimes pension funds will find that their members get their information from elsewhere like a social group or social media or AI aggregators but the information is not necessarily correct and that’s dangerous because by then it’s too late," said Betermier.
"What's doubly dangerous is if you have social media picking up on a fund acting and the information is not necessarily correct, but then I come in as another member and I use ChatGPT to say what goes on in my fund because I know they'll quickly summarize and get the information. The aggregated information may actually be wrong,” he added, noting that leaves funds racing to ensure their own content is what AI tools surface first because members "might not even come to the website. They might only interact with their own AI machine," said Betermier.
"This is more making sure that in the age of AI, members are getting the correct information from you in a way that is efficient, but in a way that doesn't just create all kinds of weird rumors, and then everything gets bypassed," Betermier added.
Liss agreed, flagging faulty AI output as one of the biggest risks facing the space right now. Fiduciary responsibility, he noted, doesn’t shift when plan administrators delegate tasks to a record keeper or an AI tool because accountability stays with the plan.
Yet, that concern laps onto a broader worry both speakers share: trust.
"The biggest asset a pension fund has is trust above and beyond the assets it actually does manage. If you lose trust, you lose a lot of credibility in the eyes of the member," said Betermier.
While Liss expects AI integration to accelerate, he underscored that organizations need to understand both the risks and the fact that liabilities remain theirs regardless of what technology sits between them and the member.
AI efficiency gains hinge on governance and liability
Still, Betermier suggests the expected productivity gains from AI are real, but only if the implementation is handled with proper governance and data protections in place.
"I think AI has profound effects because it can make us much more efficient at several tasks that used to take more time. It has to be done really well. You cannot move too fast into it. I know funds are taking their time to make sure that it's done well," said Betermier.
Liss agreed that while AI will drive efficiencies, he argued its limits are baked into the nature of the work, particularly as "AI doesn't have emotion and emotion has a role in investing as well and making people comfortable with the decisions that they're making," he said.
On the consulting side, he sees potential in making quarterly reports - covering industry trends, economic data, and fund performance - more accessible to HR leaders, CEOs, and CIOs who oversee pension plans. For instance, he points to features like clickable definitions or scannable term explanations could replace the need to dig through an appendix.
He expects AI to eventually help with drafting member communications and consolidating information on the administrative side but emphasized that anything resembling advice should stay out of AI's reach.
Still, he draws a parallel to the early internet, which expanded access to information without eliminating the need for human judgment. He expects AI to follow a similar path.
"There'll always be a need for the human perspective," he said.