Total portfolio approach treats market benchmarks as useful but not the goal
In a recent article about the “Total Portfolio Approach” it uses to manage its $860 billion portfolio, CPP provided a cogent (if not necessarily intentional) defense of tracking error, when deviating from benchmarks serves the greater, long-term good.
TPA interrogates every decision through the lens of “Will this help us achieve our (very) long-term goals?” and treats market benchmarks as useful, but not the goal. There is a certain liberty in this perspective. It allows you to take measured decisions and dismiss interim volatility as noise, media stories be damned.
Compare this to the Strategic Asset Allocation model most investors employ, where trustees judge fund success based on portfolio performance against a simple weighted index. Individual asset managers are given benchmarks and sent packing when they fail to beat them. It is a focus on the health of individual trees while TPA tries to monitor the overall forest.
This focus on tracking error got us thinking about what we’re seeing in the broader institutional landscape. Highly concentrated gains in recent years have left many active managers behind their benchmarks. This persistently high tracking error seems to be testing the patience of consultants and institutional investors who must in turn must explain “underperformance” to their members.
Below we make the case for continued patience and tolerance of tracking error, and against capitulation – especially right now – to the allure of passive or tightly constrained tracking error core options.
Value added requires tracking error
Portfolio theory’s most sacrosanct principle is that you don’t get return without risk. First, what is risk?
Tracking error (TE) is the variability of your returns versus the index. Skilled managers capture upside in rising markets and protect against the downside when markets weaken. The key element here is time. If you assess a manager on their skill at market extremes or over less than a four-to-five-year market cycle, you risk making a mistake. Good portfolio managers are planting seeds that will mature several years down the road; the trick is not chopping off the stem before it’s flowered.
If you accept that some TE is required for returns to differ from the index, and you are successful in selecting a skilled manager, you should expect them to outperform over a (sometimes very long) cycle and have every right to hold them to account. They need to generate returns above the index to compensate you for risk, after they’ve been paid.
Going passive is not zero risk
Put simply, good active management is a risk-adjusted return maximizing activity – achieved by buying the good companies and avoiding the bad ones. This is the downside-protection or path dependency part. When investors today feel the heat of seemingly chronic under-performance versus benchmarks, it’s easy to say, “Forget it – active management isn’t worth it. We’re paying fees to lag the index!”
Again, this is a question of timeframe. Many investors lost patience with underperforming active strategies (and their managers) in the 2000 dot-com craze, leading many price-disciplined managers to lose clients in this period, including us. Distrustful of management’s forecasts, we never held a share of Nortel at Leith Wheeler, a Value discipline that felt tough on the run up, and yielded a benefit to clients obvious only on the way down.
We’d argue we are in a similar environment today. Moving from a portfolio that is actively discerning value over possible hype, to a passive one that blindly buys a momentum-driven, highly concentrated, possibly overvalued market, is not a risk-mitigating decision. It manages for TE but accepts – when the fall comes – to bear the full brunt of that fall.
Would you rather have a higher solvency ratio or a tighter relative-performance track record?
Has this risk already been managed?
The success of the Yale model encouraged institutional investors to boost private asset allocations in their portfolios. It targeted long-term liabilities with long-term cash flows and its infrequent marks to market “smoothed” reported performance, thus reducing the volatility of returns, one measure of the riskiness of portfolios.
One benefit of TPA is that risk is measured and managed at the total portfolio level. You can watch sector-level exposures across aggregated equity mandates, sources of volatility can be isolated, and overall portfolio volatility (both absolute, and relative to liabilities) can be managed.
In that context, we leave readers with two related questions: With many plans’ 25 per cent-plus allocations to privates dampening total portfolio volatility, might that not free up risk budget for active strategies (rather than entice administrators to manage it down)? And by the same token, is throttling tracking error in individual active equity strategies foregoing potential return to manage a risk that’s already been handled at the top?
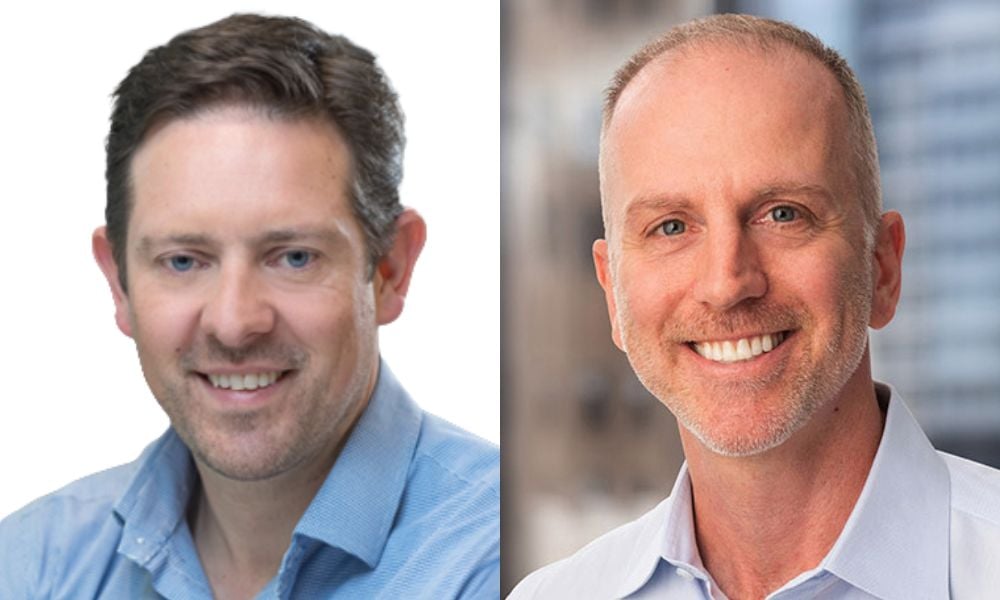
Marc Williams, CFA FCIA FIA is Principal, Portfolio Manager - Institutional Clients at Leith Wheeler Investment Counsel Ltd. and sits on the Investment Committee for BC Children’s Hospital Foundation.
Mike Wallberg, CFA is Principal, Head of Marketing & Communications at Leith Wheeler and sits on the board and serves as Vice Chair of the Investment Committee for Vancouver Foundation.