For a generation that increasingly banks from their phone, a ‘digital-first’ experience can boost participation in a group retirement plan
This article is sponsored by BMO Global Asset Management
Participation is the whole point of a group retirement plan—but for many employees, the experience of enrolling in one may not reflect how they seamlessly manage the rest of their financial lives.
In our previous article, 1 we looked at the hidden cost layers buried inside traditional group plans and how an ETF-based, transparent fee structure changes the math for both sponsors and employees. This time, we’re looking at the other half of the equation: the member experience. Specifically, how the BMO|LINK Workplace Savings Platform, a collaboration between BMO Asset Management Inc. and LINK Investment Management Inc., was built from the ground up as a ‘digital-first’ plan, and what that actually means for the people using it.
Legacy plans were built for a different era
Traditional group retirement platforms have undergone significant change to keep pace with evolving regulatory and recordkeeping requirements, but that evolution can come at a cost. For some organizations, the accumulated layers of functionality on top of legacy infrastructure can mean that everyday member interactions still rely on manual processes and offline touchpoints:
- Enrolment processes that rely on manual forms, mailed PINs, or in-person sessions
- Contribution or beneficiary updates that require participants to contact a call centre or their employer
- Investment changes that involve advisor coordination, scheduling, or follow-up meetings
- Delays in onboarding new plan members due to manual workflows between employers and service providers
Every one of these steps is a moment where an employee can disengage—or never engage at all. That’s the problem a digital-native platform is built to solve. Rather than simply moving paper forms online, it rethinks the entire member experience around the assumption that most people will interact with their retirement plan the same way they interact with their banking, bill payments and the rest of their financial lives: on a desktop or phone, in a few minutes, without picking up the phone.
How BMO|LINK removes the friction
The BMO|LINK Workplace Savings Platform was built around this ‘digital-first’ idea from day one—consolidating the full savings experience and enabling employees to contribute to an employer-sponsored Group Retirement Savings Plan (RRSP), Group Tax-Free Savings Account (TFSA), Deferred Profit-Sharing Plan (DPSP), or Multi-Employer DC Pension Plan (MEPP), all invested through a range of BMO ETFs.2
For employees, this is how it plays out in practice:
A simple online application, accessible on desktop and mobile, guides new members through a series of 13 questions to determine their risk profile,3 time horizon and investment objectives. From there, the platform recommends a personalized investment portfolio—built from a mix of BMO ETFs and managed by LINK—so they can begin their savings journey immediately. There’s no paper Know Your Customer (KYC) form, no mailed PIN, and no waiting on an advisor’s calendar.
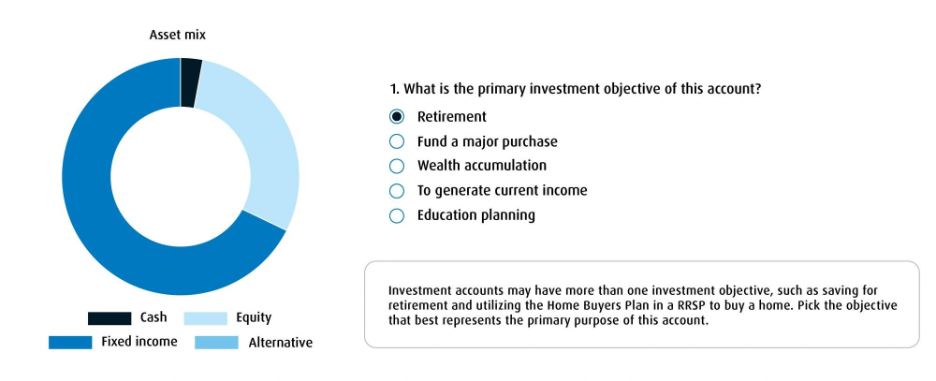
For illustrative purposes only.
2. Portfolios that adjust themselves. Once invested, members are placed into one of a range of portfolios—from Income to Equity Growth—based on their profile. These portfolios are automatically rebalanced on a quarterly basis, so members don’t need to monitor markets or make ongoing trading decisions. As life circumstances change—a new job, a marriage, an approaching retirement date—members can update their profile and shift portfolios just as easily.
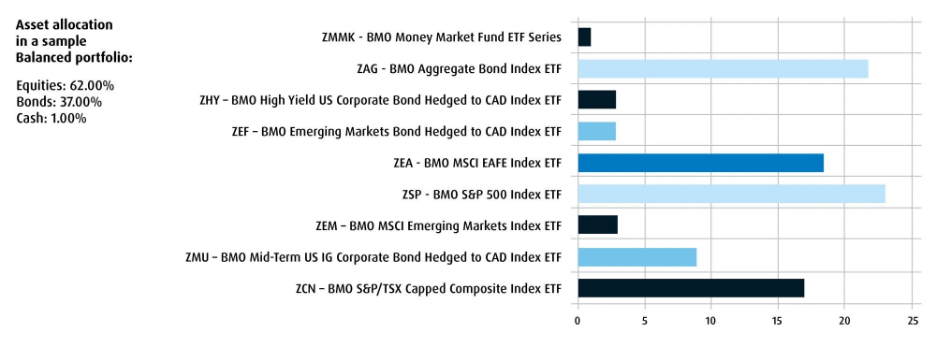
For illustrative purposes only.
3. Visibility that’s always on. Instead of waiting for a quarterly statement, employees can log into their personal online dashboard anytime—on desktop or mobile—to track investment performance, adjust contributions, request withdrawals, or pull a tax receipt. This kind of visibility tends to build trust in the plan, simply because members can see exactly what’s happening with their money, in real time. And for those who still want to talk to someone, real-time support from customer service representatives is available too.
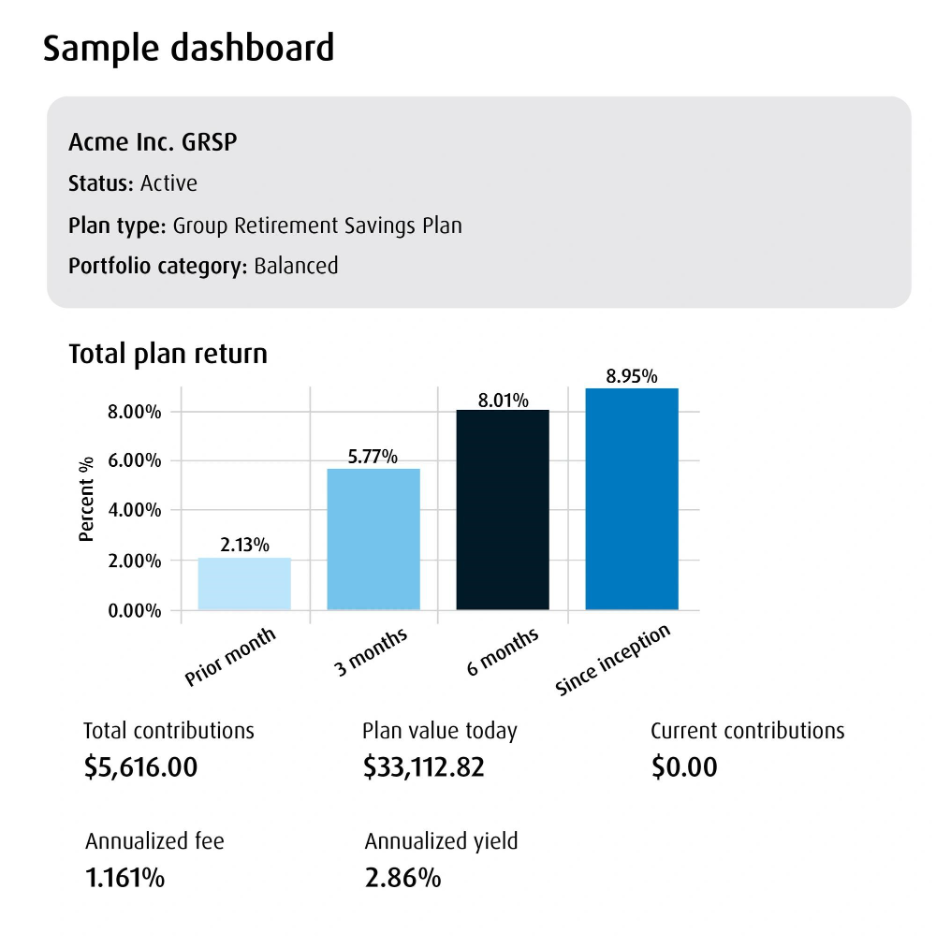
For illustrative purposes only.
For plan sponsors and administrators, minimizing friction isn’t limited to the employee experience. Payroll and Human Resources Information System (HRIS) integrations automate the flow of demographic and contribution data, removing a major source of manual uploads and reconciliation work. A modern administrative dashboard with self-serve reporting and templated onboarding workflows means new sponsors can get a plan up and running faster, with less back-and-forth.
And ‘digital-first’ doesn’t mean digital-only. Bilingual client success teams and AI-assisted triage are built into the platform, so when members or administrators do need help, they get a fast first response—without being routed through multiple departments.
Put side by side, the difference in friction—for both employees and plan sponsors—becomes clear:
|
|
Traditional legacy plan |
BMO|LINK ‘digital-first’ plan |
|---|---|---|
|
Enrolment |
Manual forms, mailed PINs, in-person sessions |
Online questionnaire, same-day enrolment |
|
Investment section |
Menu of investment options or advisor meeting |
Personalized recommendation via 13-question robo-advisor |
|
Portfolio management |
Manual rebalancing, employee-driven decisions |
Automated quarterly rebalancing |
|
Account access |
Quarterly statements, limited online tools |
Real-time dashboard, accessible on desktop and mobile |
|
Contribution/withdrawal changes |
Call centre, paper requests |
Self-serve online |
|
Admin reporting |
Manual or ad hoc |
Self-serve admin dashboard with templated reporting |
|
New sponsor onboarding |
Lengthy, manual setup |
Templated, faster time-to-launch |
|
Support model |
Standard call centre queues |
Bilingual support with AI-assisted triage; LINK portfolio management team also available as needed |
The bottom line
A retirement plan only works if people actually use it. Low fees and good investments matter—but so does whether an employee can enrol in minutes from their desktop or phone, see exactly where they stand at any given moment, and trust that their portfolio is being managed appropriately without having to think about it.
The BMO|LINK Workplace Savings Platform was designed around that reality. By removing the friction points that have historically kept group plan members disengaged—slow enrolment, opaque statements, manual processes on both sides—it gives employers a way to offer modern, transparent ETF-based plans that employees are more likely to actually use. And for plan sponsors, the same digital infrastructure that improves the member experience also reduces the administrative burden of running the plan day to day.
Sources
1 BMO Financial Group, “What you pay matters: Understanding ETF-based group plan fees,” May 28, 2026.
2 BMO Financial Group, “From cost drag to cost smart: How ETFs are reshaping group retirement,” April 15, 2026.
3 Risk profile: One’s risk profile is comprised of risk tolerance (i.e., willingness to accept risk) and risk capacity (i.e., ability to endure potential financial loss).
Disclaimers:
This content is sponsored by BMO Global Asset Management (BMO GAM). Benefits and Pensions Monitor was compensated by BMO GAM for this article. Benefits and Pensions Monitor is an independent organization and is not affiliated with BMO GAM.
This article is for information purposes only. The information contained herein is not, and should not be construed as investment, tax or legal advice to any party. Particular investments and/or trading strategies should be evaluated and professional advice should be obtained with respect to any circumstance.
The viewpoints expressed in the material represent the assessment of the markets at the time of publication. Those views are subject to change without notice at any time. The information provided herein does not constitute a solicitation of an offer to buy, or an offer to sell securities nor should the information be relied upon as investment advice. Past performance is no guarantee of future results.
Any statement that necessarily depends on future events may be a forward-looking statement. Forward-looking statements are not guarantees of performance. They involve risks, uncertainties and assumptions. Although such statements are based on assumptions that are believed to be reasonable, there can be no assurance that actual results will not differ materially from expectations. Investors are cautioned not to rely unduly on any forward-looking statements. In connection with any forward-looking statements, investors should carefully consider the areas of risk described in the most recent simplified prospectus.
The BMO|LINK Workplace Savings Platform is a software-as-a-service platform managed by LINK Investment Management Inc. (“LIM”). LIM is a corporation incorporated under the laws of Canada and has its head office in Calgary, Alberta. LIM provides business solutions for workplace savings and pension plans, using innovative, fully digital, software-as-a-service business solutions to empower plan administrators and plan members with simple, affordable and efficient plan management. LIM has retained LINK Plan Management Inc. (“LPM”), a wholly-owned subsidiary of LIM, to act as the full discretionary portfolio manager to employees who open accounts with LPM under the BMO|LINK Workplace Savings Platform. LPM is a corporation incorporated under the laws of Canada and has its head office in Calgary, Alberta. It is registered as a portfolio manager in Alberta, British Columbia, Manitoba, New Brunswick, Nova Scotia, Ontario, Quebec, and Saskatchewan. Its principal regulator is the Alberta Securities Commission. LPM’s registration is subject to terms and conditions related to its use of an online “know your client” process for its operations, which restricts LPM from using margin, short selling or a leveraged investment strategy in its clients’ managed accounts, and restricts its clients’ managed accounts to only be invested in mutual funds, including exchange traded funds that are not commodity pools and do not use short selling or a leveraged investment strategy and cash and cash equivalents. LIM and LPM retained BMO Asset Management Inc. (“BMOAM Inc.”) as its marketing representative and agent to market the administrative services provided by LIM in respect of the BMO|LINK Workplace Savings Platform. LPM has retained BMOAM Inc. as its sub-advisor to provide investment advisory services to LPM in respect of the accounts. BMOAM Inc. is a wholly-owned subsidiary of Bank of Montreal, and Bank of Montreal holds a minority ownership position in LIM. Under the BMO|LINK Workplace Savings Platform, LPM will invest in investment products manufactured and/or advised by BMOAM Inc., including BMO ETFs (collectively, “BMO Products”). To the extent that LPM makes BMO Products available to its clients using the BMO|LINK Workplace Savings Platform, LPM will do so in compliance with its current policies and procedures and applicable laws and regulations, including LPM’s duty to resolve any conflicts of interest in the best interests of its clients. LPM, as portfolio manager to employees who open accounts, is ultimately responsible for investment decisions made in connection with the BMO|LINK Workplace Savings Platform. Questions regarding the BMO|LINK Workplace Savings Platform or any investment decisions or advice provided by LPM should be directed to LPM.
Commissions, management fees and expenses all may be associated with investments in exchange-traded funds. Please read the ETF Facts or prospectus of the BMO ETFs before investing. Exchange-traded funds are not guaranteed, their values change frequently and past performance may not be repeated. For a summary of the risks of an investment in the BMO ETFs, please see the specific risks set out in the BMO ETF’s prospectus. BMO ETFs trade like stocks, fluctuate in market value and may trade at a discount to their net asset value, which may increase the risk of loss. Distributions are not guaranteed and are subject to change and/or elimination. BMO ETFs are managed by BMO Asset Management Inc., which is an investment fund manager, a portfolio manager, and a separate legal entity from Bank of Montreal.
BMO Global Asset Management is a brand name under which BMO Asset Management Inc. and BMO Investments Inc. operate.
“BMO (M-bar roundel symbol)” is a registered trademark of Bank of Montreal, used under licence.of Montreal, used under licence.