Oil-weighted producers eye 10% output growth as institutional sentiment shifts toward Canadian energy expansion
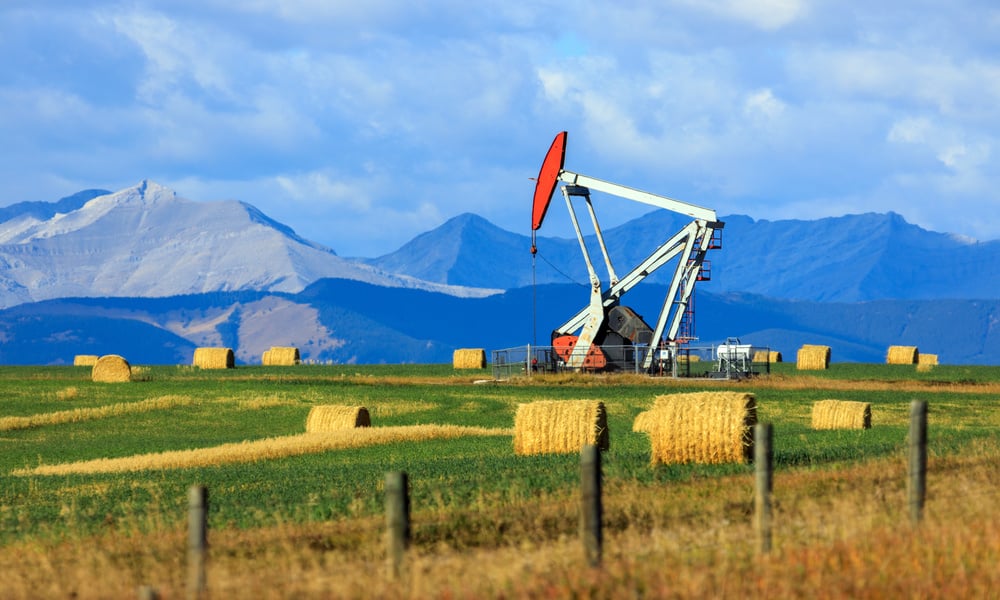
Institutional investors now favour growth spending over share buybacks and debt repayment in Canadian energy. It is the first time this has happened since ATB Cormark Capital Markets began its energy survey in 2021.
In its Fall 2026 Energy Sector Survey, 41% of institutional investors ranked growth spending first, up from 18% in spring 2026. The September 14 to 28 survey drew 91 responses from 42 institutional investors and executives at 27 exploration and production (E&P) companies and 22 energy services companies.
The comparison draws on different samples. The spring survey included 17 institutional investors among its 63 participants.
“Institutional investors are also becoming less defensive, preferring growth spending over buybacks and debt repayment for the first time in the Survey’s history,” said Tim Monachello, managing director, institutional research at ATB Cormark Capital Markets.
Canada’s four biggest oil sands producers generated more than $14 billion in combined free cash flow or free funds flow in the second quarter. Executives told investors shareholder returns would remain their top priority. Suncor said it would raise monthly buybacks from $350 million to $500 million beginning in August.
Bullish sentiment, cooler outperformance calls
Over the past six months, 76% of institutional investors became more bullish on energy, and 61% increased their net energy exposure. Nearly four in five consider Canadian energy equities undervalued.
In February, PenderFund’s Geoff Castle described energy equities and credit as attractively priced and said energy offers institutional investors liquidity.
Some 63% expect the sector to outperform the S&P/TSX Composite Index over the next year, down from 76% in spring 2026.
Energy made up 17.4% of the index at the end of July.
RBC Investor Services data show energy jumped 30.1% in Q1 2026 after the Strait of Hormuz closure, partly offsetting a 22.5% slide in technology.
Energy then fell 5.0% in Q2 after oil prices retreated, while defined benefit plans posted a 6.0% median return.
Middle East disruption turns attention to Canada
Constraints on Middle Eastern crude oil and liquefied natural gas (LNG) exports have made 79% of institutional investors more likely to invest in Canadian energy. Across all groups, 72% expect long-term global crude balances to be tighter than they had expected before the conflict.
A recent analysis said the war in Iran is pushing pension investors to stress-test country exposure through an energy lens. Canada sends more than 90% of its energy exports to the US.
Prices seen easing
Most respondents (61%) expect oil prices to fall over the next year from the roughly USD98 per barrel survey-period average. Over three to five years, 53% of E&P and institutional respondents expect West Texas Intermediate (WTI) crude to average above USD75 per barrel, up from 43% in spring 2026 and 38% in fall 2025.
CME Group data show November WTI futures were quoted at USD94.23 per barrel on October 14.
On natural gas, 42% expect higher short-term prices and 6% expect a decline, while longer-term expectations have softened.
Activity set to climb in 2027
Among E&P respondents, 96% expect higher production over the next year, up from 88% in fall 2025. Oil-weighted producers anticipate about 10% growth and gas-weighted producers about 5%, and 56% expect higher exploration and development spending in 2027.
The survey points to approximately 5%–10% growth in Canadian field activity and E&P capital spending in 2027.
“What’s notable is that companies are planning to grow even with an expectation that oil prices will normalize into a lower range over the next year,” said Monachello.
Among services respondents, 81% expect activity to rise from current levels, and 90% expect more customer activity on average in 2027 than in 2026. After margin pressure a year ago, 71% report a better outlook over the past three months, none report deterioration, and 57% expect margins to improve over the next six months.
For the first time since fall 2022, more services respondents report excess demand than excess capacity. Companies expect higher activity to support improvements in pricing and margins, though rising input costs remain a concern.
Export projects gain ground in Ottawa
Some 89% view the federal government’s approach to growing the industry positively, and strong majorities expect positive final investment decisions for Pacific Link/Pathways, Prairie Connector and Ksi Lisims.
Darren Eurich, CEO of ATB Cormark Capital Markets, said the improved outlook “matters for an industry that needs access to more markets.”
On October 1, Ottawa named Pacific Link, a proposed West Coast oil pipeline, the first project of national interest under the Building Canada Act. Construction is targeted for September 2027.
Several of Canada’s largest pension funds told Ottawa they stand ready to buy Canadian airports, with wish lists extending to pipelines and electricity grids.
West Coast LNG expansion remains the top-ranked opportunity. Federal energy and environmental policies remain the top-ranked risk, though concerns have moderated.