OMERS’ chief pension officer calls for multi-stakeholder action, modernizing access to scale DB coverage beyond the public sector
Each month at BPM, we offer a slate of articles and content pieces that go deep on a particular topic. This month, we're focusing on defined benefit (DB) plans.
Despite Canada’s defined benefit (DB) pension plans producing strong funded positions, access remains stubbornly limited, particularly as most DB coverage sits in the public sector, and millions of private-sector workers still don’t have a workplace pension at all.
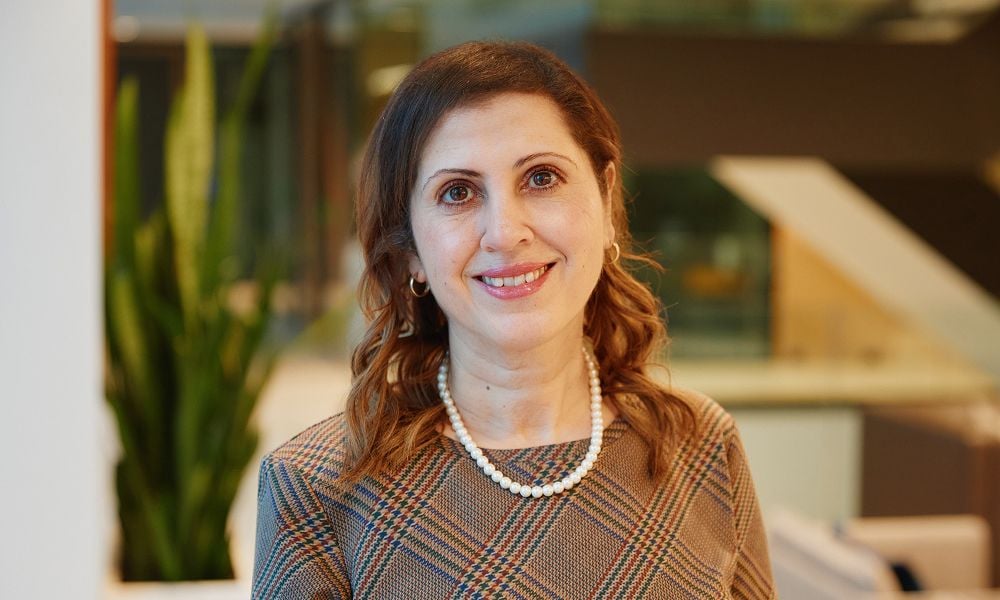
As Celine Chiovitti, chief pension officer at OMERS, suggests, this isn’t a design flaw in the DB model but rather a failure to scale what works.
"The average worker does not have the capacity on their own to be able to even contemplate how much they would need to save in order to live in the future, in their retirement," she says. “From a DB perspective, the risk is taken away from the individual. When you can find a way that you can demonstrate to do that, to build with scale, to invest globally, to keep fees low, and then also to just continue to provide what we call the pension promise. At the end of the day, it really is the building blocks for future sustainability.”
But when asked whether these types of plans can also deliver comparable outcomes, she underscores that having pension access is better than none.
"Any pension plan is better than no pension plan. I think if you were to look at all of the plans and it is feasible for you, plan sponsors should explore DB as one of the ones that provide the greatest ability to provide that stability dividend that we're seeing," adds Chiovitti.
The case for DB as the gold standard
While Chiovitti sees jointly sponsored pension plans as part of the solution, she doesn’t see them as the be-all and end-all. According to Chiovitti, DB plans are reclaiming their status as the gold standard after a period of decline, driven by what she sees as predictability, lifetime income, and access to institutional-grade investment management at lower cost.
DB plans are a recruitment and retention tool that employers are undervaluing, says Chiovitti. With Canadians living longer than any previous generation, the longevity risk facing individual workers is enormous, and most have no realistic way to manage it alone. She points to the data that supports the case, highlighting earlier research conducted by the Canadian Centre for Economic Analysis (CANCEA) on behalf of OMERS, which found that members with DB pension access reported significantly higher life satisfaction, better physical and mental health, and stronger financial security than the general Ontario population.
Those outcomes extend beyond the individual as financially secure retirees give back to their communities at higher rates, volunteer more, and rely less on government supports, says Chiovitti.
Structural barriers holding back DB coverage
Yet, she identifies three structural barriers holding back DB coverage: affordability for employers, the scale required to make plans viable, and outdated rules that no longer reflect how Canadians work. While DB plan membership grew by approximately 4.3 per cent in 2023, according to StatsCan data, Chiovitti says the gains remain concentrated in the public sector and skew toward women because of that sector's workforce composition.
Moreover, she acknowledges that Canada's three-tier retirement system, which consists of employer-sponsored plans, government benefits and personal savings, depends on employer-sponsored plans functioning as a load-bearing middle pillar. When most workers cannot reach that tier, the other two fall apart as the system was designed to work together.
“When we talk about some of the barriers, the reality is many of these plans were created back in the 1960s, and we do need to modernize them to make them more flexible and to make them represent the workforce that we're living in today,” says Chiovitti. “Whether it's addressing some of the gender pension gap issues, or just modernizing some of our tools and technology, we do need to find a way to have these types of plans resonate with a younger, more mobile workforce.”
Modernizing plans for a mobile workforce
Chiovitti disagrees with the idea that a mobile, gig-oriented workforce has outgrown the DB model. Vesting means members build toward future wealth while employed, and the benefit stays with them if they leave. While individual investors can buy mutual funds, she emphasizes how they can’t access the institutional scale, diversification, and fee structures that large, pooled plans deliver.
Chiovitti also acknowledges how the shift is generational, noting how younger workers are paying closer attention to pension quality when choosing employers. Moreover, retirement income for the next generation will likely come from multiple sources rather than a single pension cheque, she argues, and the industry needs to build the financial planning tools to help members see how those pieces fit together.
She points to OMERS' youngest member, who is 14 years old. She underscores that this worker's career will almost certainly not be a straight line to retirement with a single employer, adding that the pension sector needs to stop designing for a career model that no longer exists and start treating DB coverage as one layer in a more complex income stack.
A multi-stakeholder path forward
To that end, Chiovitti calls for a multi-pronged approach that begins with acknowledging that Canadians aren’t saving enough and the savings vehicles available to most workers are inadequate. She emphasizes that regulators, policymakers, employers, unions, and pension plans need to stop working in silos and confront that affordability gap together, discussing what pensions should look like for the next generation. Chiovitti underscores the barriers won’t fall without coordinated action.
After all, the main priority is expanding access to credible long-term savings options and modernizing the retirement system to match a workforce whose careers no longer follow a straight line. As more workers move away from traditional hours, take career breaks or take on contract and gig work, she believes pension design needs to account for that.
Additionally, outdated provisions in the Income Tax Act and other legislative frameworks are actively constraining access, and no single stakeholder can dismantle them alone, she says.
"What are we trying to solve for? I think if we could start by just articulating the problem and working backwards, there's nowhere to go but up," says Chiovitti.