Eckler's Murray Wright warns plan sponsors to track membership shifts before funding choices narrow
Pension plan sponsors spend considerable time tracking market volatility, interest rate movements, and inflation but one pension expert argues that demographic change deserves equal attention, even though it operates on a different timescale. Moreover, plan sponsors should prepare themselves for more than one future.
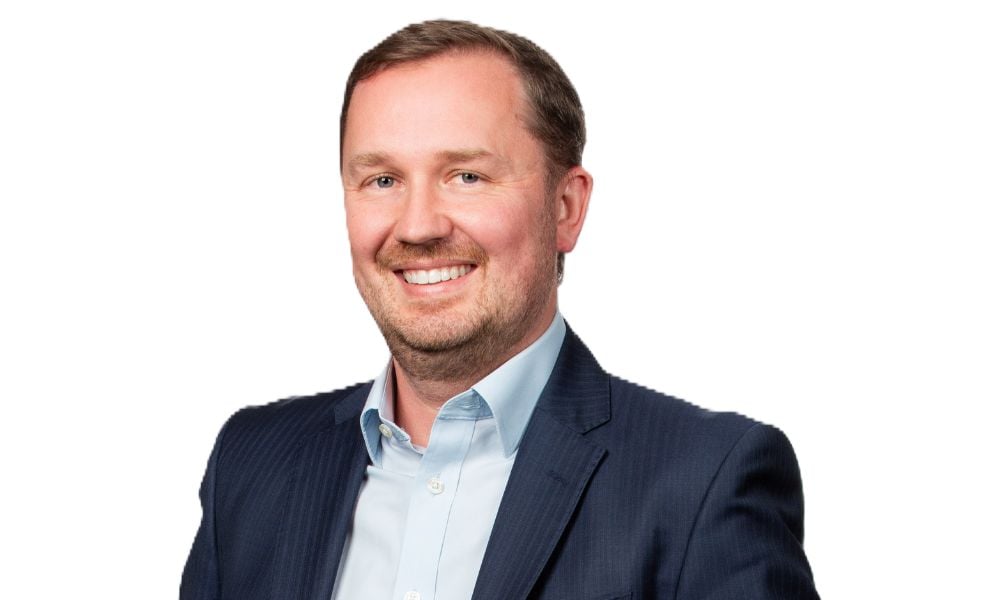
"Investment returns are going to be the main driver of success or failure of a pension plan over time. But the demographic stuff that happens more gradually can be just as consequential," said Murray Wright, senior director and consulting actuary in Eckler's pension practice in Vancouver.
"There's still lots of uncertainty into the future, but there's lots more structure around demographics. It's much more predictable. There's tighter parameters about what can happen because we're dealing with humans. We broadly know roughly when they're going to retire. We have an even better understanding of how long people are going to live. To some extent, the future has already arrived with demographics. We know what your plan members look like, who they are today, and we can take advantage of that," added Wright.
Wright, who’s also a fellow of the Canadian Institute of Actuaries, presented at the Canadian Pensions and Benefits Institute (CPBI) Western Canada regional conference on Tuesday, highlighting how plan sponsors can use demographic analysis to anticipate financial risk rather than react to it after the fact.
He drew a distinction between the visible disruptions that dominate board agendas and the structural membership changes that accumulate beneath them. Market shocks are "the smoke alarm blaring in the kitchen," he said, while demographic drift is "the slow gas leak in the basement. They're both still very important. We need to pay attention to both of them."
What leads to financial risk
Wright explained the mechanism through which demographics become financial risk, noting as a plan matures and the ratio of active members to retirees declines, cash flows shift. Contributions shrink relative to benefit payments, and the plan moves from being a net buyer of assets to a forced seller.
"Every month you're having to sell down a particular piece of your assets to rebalance things. And that's fine until markets are having a downturn and you're selling through that downturn," Wright said, underscoring that negative cash flows are common across Canadian plans, but as the imbalance grows relative to total assets, it constrains investment capacity and erodes funding resilience.
Wright illustrated this with two hypothetical plans, both funded at 105 per cent with identical assets and liabilities. One has a growing active membership and neutral cash flows while the other is shrinking, with negative cash flows and a deteriorating active-to-retired ratio.
"Despite it being the same funded ratio and that being a very important metric, you would and should manage these two plans quite differently," he said, noting the demographic profile should inform investment risk tolerance, funding policy, and how the board communicates risk appetite.
While Wright agrees that DB plan sponsors are paying closer attention to their funded positions than they were a decade ago, he questions whether boards are examining what sits underneath those numbers. The standard actuarial assumption - a stable population of new entrants projected indefinitely - is a reasonable starting point, he said, but it can mask structural change that compounds over decades.
What happens when new entrants change
He urged trustees to test three scenarios during asset liability modelling: more members, fewer members, and different members. He suggests the third matters most.
"What if the members coming in are older or younger? They have different jobs and occupations, the workforce is changing over time," he said.
Wright pointed to 2026 Statistics Canada data that found the median retirement age in Canada has climbed back above 65 after falling to nearly 60 around the turn of the century - a pattern Wright believes too many plans have been slow to absorb.
"If half the plan is retiring after the normal retirement age, we should maybe think about that and think about how to deal with that," he said.
That shift also carries implications for how actuaries and consultants model pension risk going forward, particularly when assumptions about retirement timing no longer reflect post-COVID member behaviour.
On the question of which levers sponsors can pull, Wright draws a line between the immediate and the generational. Eligibility rules and funding policy margins can be adjusted quickly while plan design, everything from contribution levels, accrual rates, retirement incentives can take years.
"It's not just amending the plan text, it's talking about all the communications that come out of it, changing your administration systems, but getting that right and matching up with the demographics of the plan and where the future of that workplace will go, that's the real long-term piece to get to," he said.
What signals sponsors should track now
To that end, Wright proposed a five-signal demographic risk dashboard covering new entrant volumes, the active-to-retired ratio, age and service profiles, retirement and mortality patterns, and net cash flows. He acknowledged that while sponsors don’t have control over demographics, “it's response and preparedness rather than influence,” he said.
Ultimately, Wright identified new entrant tracking as the single most powerful forward-looking indicator available to plan sponsors. Small changes in new entrant growth rates, compounded over decades, produce vastly different outcomes for plan maturity and financial sustainability.
He modelled scenarios in which shifting the new entrant growth assumption by just a few percentage points, from -1 per cent to +2 per cent, moved a plan from having more retirees than active members to having two actives for every retiree.
"It's these small incremental changes in new entrants over time that can give you a completely different endpoint," he said.
Still, he argued sponsors should test their long-term projections against scenarios with more, fewer, and different members, not just the standard assumption that the current population persists indefinitely.
As to how sponsors should distinguish a short-term hiring blip from a permanent structural shift, Wright conceded there’s no one formula.
"It's about talking with the experts. You'll have people in the boardroom that have worked in the industry or supporting the industry, and they might have seen it all before. A lot of it is just asking the right questions or encouraging your advisors and the people supporting the plan to think about it before they bring the best advice to you," he said.